ARM vs. Fixed-Rate Reverse Mortgages: Which Option Best Supports Your Retirement Goals?
For many homeowners age 62 and older, a reverse mortgage can be a powerful tool for improving cash flow, eliminating an existing mortgage payment, or creating a more secure retirement strategy. One of the most important decisions you'll make is whether to choose a fixed-rate or adjustable-rate reverse mortgage.
While both options allow eligible homeowners to convert home equity into usable funds without required monthly principal and interest payments, they serve very different purposes.
Understanding the Basics
Most reverse mortgages today are Home Equity Conversion Mortgages (HECMs), which are insured by the Federal Housing Administration (FHA). Regardless of whether you choose a fixed or adjustable rate, you'll receive important borrower protections, including:
No required monthly principal and interest payments
Non-recourse protection
The ability to remain in your home as long as you meet loan obligations
FHA insurance protections on HECM loans
The difference lies in how you access your equity and how the loan is structured.
Fixed-Rate Reverse Mortgages: Simplicity and Predictability
A fixed-rate reverse mortgage provides one major advantage: the interest rate never changes during the life of the loan.
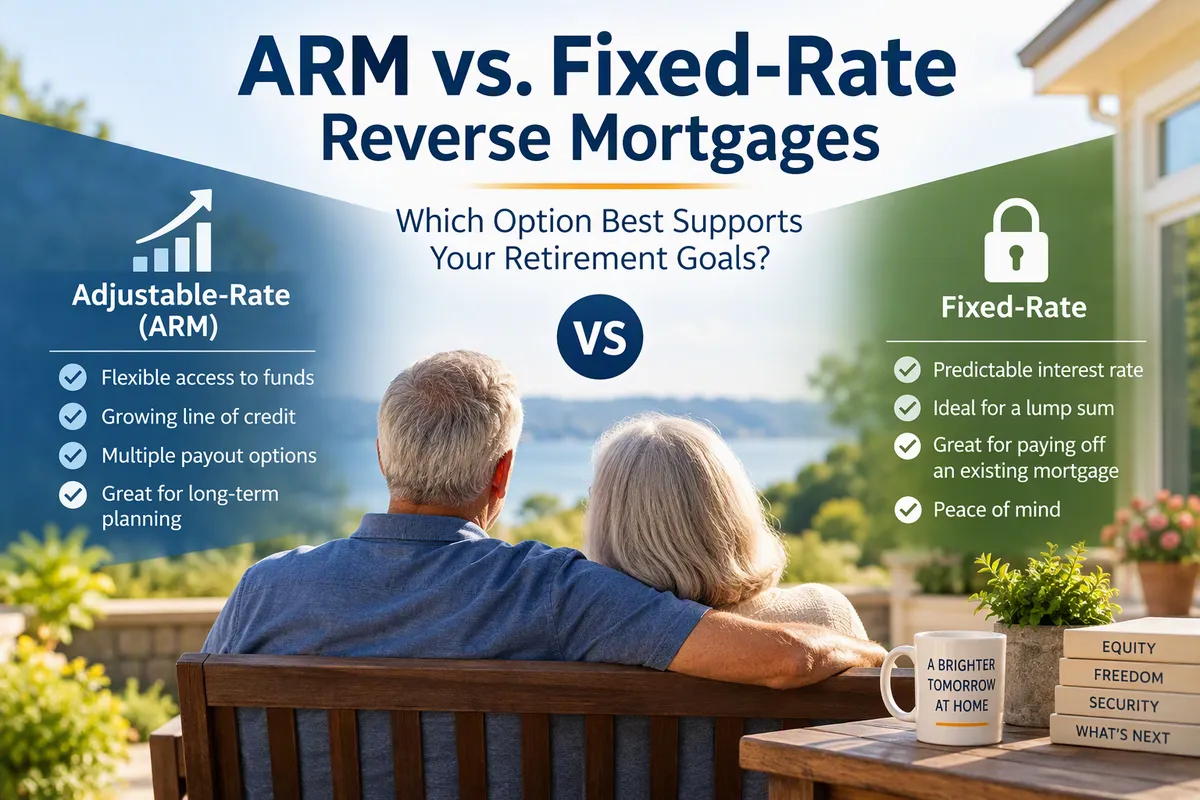
Many borrowers choose a fixed-rate option when they need a substantial amount of money upfront, particularly to pay off an existing traditional mortgage. Eliminating that monthly payment can significantly improve retirement cash flow.
Benefits of a Fixed-Rate Reverse Mortgage
Predictable interest rate
Ideal for paying off an existing mortgage balance
Simple loan structure
Peace of mind from rate stability
Potential Drawbacks
Fixed-rate reverse mortgages are generally structured as closed-end loans. In most cases, funds are disbursed primarily as a lump sum at closing, subject to FHA disbursement limitations. Any unused borrowing capacity is typically not available later. This means:
No future draws
No line of credit
Less flexibility if financial needs change over time
Adjustable-Rate Reverse Mortgages: Flexibility for the Future
An adjustable-rate HECM works much differently.
Instead of receiving all available proceeds upfront, borrowers can access funds over time through multiple payout options. The interest rate is tied to a market index plus a lender margin and can change periodically.
Many homeowners initially hear "adjustable rate" and become concerned. However, unlike a traditional mortgage, there is no required monthly mortgage payment based on rate changes. An increase in the interest rate affects how quickly the loan balance grows, not a monthly payment you must make.
Benefits of an Adjustable-Rate Reverse Mortgage
Line of credit access
Monthly tenure payments for life
Term payments for a specific period
Combination payment options
Greater control over when and how funds are used
Perhaps the most compelling feature is the growing line of credit. Any unused available credit can increase over time, creating additional borrowing capacity for future needs.
This can make an adjustable-rate HECM especially valuable for:
Retirement income planning
Healthcare expense preparation
Emergency reserves
Market downturn protection
Long-term wealth preservation strategies
The Often-Overlooked Credit Line Advantage
One reason financial planners increasingly discuss reverse mortgages as a retirement planning tool is the HECM line of credit feature.
Instead of drawing all available funds immediately, borrowers can leave a portion unused. That unused credit may grow over time, giving homeowners access to a larger reserve in future years.
For retirees concerned about longevity risk, unexpected expenses, or market volatility, this flexibility can be extremely valuable.
What About Proprietary Reverse Mortgages?
Proprietary reverse mortgages, sometimes called jumbo reverse mortgages, may also offer fixed and adjustable-rate options.
However, unlike FHA-insured HECMs, the rates, lending limits, loan-to-value calculations, and rate lock policies are determined by the individual lender or investor. These programs can change more frequently and may vary significantly from one lender to another.
Which Reverse Mortgage Makes the Most Sense?
The better question isn't necessarily, "Which rate is lower?"
Instead, ask:
What do I need this reverse mortgage to accomplish?
A fixed-rate reverse mortgage may be best if:
You need a large amount of cash immediately.
You're primarily paying off an existing mortgage.
You value interest-rate certainty.
An adjustable-rate reverse mortgage may be best if:
You want future access to your home's equity.
You prefer a line of credit strategy.
You need flexible retirement income options.
You're taking a long-term retirement planning approach. [reverseplus.com]
Final Thoughts
A reverse mortgage can be much more than a way to eliminate a mortgage payment. When structured properly, it can become an important component of a comprehensive retirement strategy.
For many homeowners, the adjustable-rate HECM's flexibility, line of credit growth, and multiple payout options make it the preferred choice. For others, the simplicity and certainty of a fixed-rate option align better with their goals.
The right answer depends on your financial objectives, cash-flow needs, and long-term retirement plans.
Before choosing either option, work with a knowledgeable reverse mortgage specialist who can illustrate multiple scenarios and help determine which strategy best supports your retirement goals.